

Key takeaways
- Transferring crypto between wallets you own is not taxable. However, you should keep records of these transfers, as they may lead to inaccurate/missing cost basis on Form 1099-DA.
- Spending crypto on transfer fees is considered a disposal subject to capital gains tax.
- Since 2025, cost basis is tracked wallet by wallet, and the coins you move keep their own cost basis.
Moving crypto between wallets you own isn’t taxable, and your cost basis and holding period carry over. The catches are network fees you pay in crypto, which count as taxable disposals, and exchanges that can’t see what you originally paid. Sending crypto to someone else’s wallet is different. Using it to pay for goods or services is a taxable disposal, while a genuine gift isn’t taxable to you, though gifts above $19,000 per recipient in 2026 need a gift tax return.
Is moving cryptocurrency between different wallets taxable?
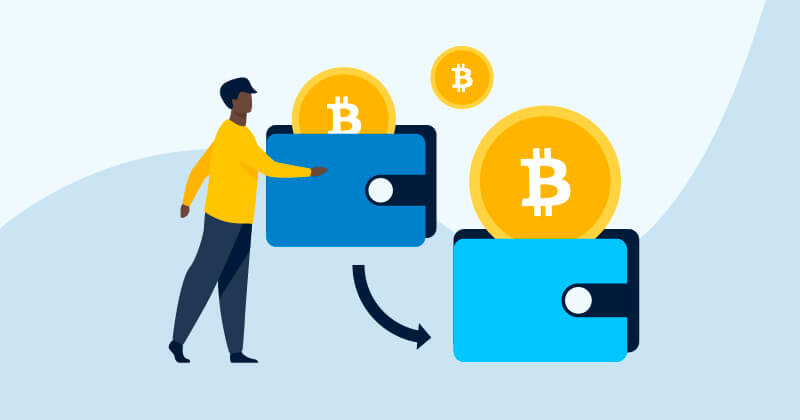
Moving cryptocurrency between wallets that you own is not taxable. The IRS has released clear guidance on this matter.
In addition, your cost basis and holding period do not change after a wallet-to-wallet transfer. Your cost basis will be your original cost for acquiring your cryptocurrency. Your holding period will be whenever you first acquired your coins.
What tax issues can wallet-to-wallet transfers cause?
If you haven’t kept accurate records of your crypto transactions, wallet-to-wallet transfers can cause issues on Form 1099-DA (more on this later).
How does the wallet-by-wallet rule affect transfers?
Since January 1, 2025, the IRS has required you to track cost basis separately for each wallet or account you own. When you move crypto, the specific units you send keep their own cost basis and acquisition date. As a result, you can no longer treat all of your crypto as one universal pool. When you sell, your gain or loss is based on the units in the wallet you sell from, so keep a record of exactly which units you moved.
To ease the transition, Rev. Proc. 2024-28 gave investors a one-time safe harbor to allocate their unused cost basis to the crypto held in each wallet or account as of January 1, 2025. That window has closed. It ended no later than October 15, 2026, and earlier for investors who sold or transferred that crypto during 2025.
For crypto held on an exchange, Notice 2026-20 extends the relief in Notice 2025-7 through December 31, 2026, which allows you to identify the units you sell in your own records without telling the exchange. For more information, check out our guide to the IRS’s new crypto cost basis rules.
How are wallet transfer fees taxed?
Summary: Fees from wallet-to-wallet transfers are likely not tax deductible. However, disposing of your cryptocurrency to pay transfer fees is subject to tax.
Are wallet-to-wallet transfer fees taxable?
While moving cryptocurrency is not taxable, spending crypto on gas fees for crypto transfers is considered a taxable disposal. According to the IRS’s digital asset FAQs, a transfer between your own wallets is non-taxable, except for any crypto you use, or that’s withheld, to pay for the transfer (IRS FAQ 81).
You’ll incur a capital gain or loss depending on how the price of the crypto you used to pay the fee changed since you originally received it (IRS FAQ 97).
If an exchange takes its withdrawal fee in crypto, that disposal can show up on the Form 1099-DA the exchange issues. Network (gas) fees you pay from a self-custody wallet aren’t reported on any 1099-DA, but you still need to report any gain or loss on your tax return. Typically, your gains/losses from these transactions are minimal.
In addition, if you paid a transfer fee in crypto, you should answer ‘Yes’ to the digital asset question on Form 1040, even if the transfer itself was between your own wallets.
Can I deduct fees from wallet-to-wallet transfers?
No, wallet-to-wallet transfer fees can’t be added to your cost basis to reduce your capital gain. The IRS says fees you pay to transfer crypto between your own wallets or accounts are not treated as digital asset transaction costs (IRS FAQ 53).
Typically, you can apply expenses to the cost basis of the property if your transaction meets one of the following conditions.
- It is a necessary part of buying or selling the property.
- It increases the underlying value of the property.
Moving crypto between your own wallets doesn’t meet either condition. The IRS hasn’t specifically ruled on whether you can deduct these fees as an expense, and most investment expenses are no longer deductible for individuals. As a result, the conservative approach is to treat wallet-to-wallet transfer fees as non-deductible.
Is sending crypto to another person taxable?
When is sending crypto to another person taxable?
If you send cryptocurrency to another person in exchange for goods or services, it will be considered a taxable disposal. You’ll incur a capital gain or loss depending on how the price of your crypto changed since you originally received it.
When is sending crypto to another person not taxable?
Sending cryptocurrency as a gift is non-taxable for all but the most generous gift givers.
While you may need to fill out a gift tax return if your gifts exceed $19,000 per recipient in 2026, this form is primarily for informational purposes. You won’t owe gift tax unless your lifetime taxable gifts (amounts above the annual exclusion) exceed $15 million, the 2026 basic exclusion amount.
Not sure what's in your wallet? You can monitor the value with this crypto wallet balance checker.
Are crypto-to-crypto transactions taxable?
Moving your cryptocurrency between wallets should not be confused with crypto-to-crypto transactions, where one cryptocurrency is traded for another. Unlike wallet-to-wallet transfers, crypto-to-crypto transactions are considered taxable.
Because you are disposing of cryptocurrency in a crypto-to-crypto trade, you will incur a capital gain or loss depending on how the value of your coins has changed since you originally received them.
Why wallet-to-wallet transfers can cause tax issues
Starting with 2025 transactions, US crypto brokers, including centralized exchanges like Coinbase, must issue Form 1099-DA. The form reports your gross proceeds from crypto you sell or trade through that broker. For sales in 2026 and later, brokers also report cost basis, but only for crypto you bought on or after January 1, 2026 and kept with the same broker. Form 1099-DA doesn’t cover disposals from a self-custody wallet or on DeFi platforms, which you still have to report yourself.
While wallet-to-wallet transfers aren’t reported on Form 1099-DA, they can cause reporting issues if you dispose of your cryptocurrency in the future. That’s because crypto you transfer into an exchange is a noncovered asset, so the exchange isn’t required to report its cost basis. As a result, the cost basis on your Form 1099-DA may be left blank.
Consider the following scenario.
In this case, David’s capital gain should be $5,000. However, the BTC came into Exchange B from a cold wallet, so it’s a noncovered asset. Exchange B’s Form 1099-DA will show $15,000 of proceeds and leave the cost basis blank. Unless David has records of his $10,000 purchase, he can’t prove his basis and could end up paying tax on the full $15,000.
Luckily, there’s an easy fix for this problem. You are allowed to report your own cost basis on Form 8949, provided that you have documentation that can back up your claims.
That’s why it’s important to keep careful records of your cost basis (or use crypto tax software to track it for you automatically).
For each transfer, keep the date and time, the asset and amount, the transaction ID (hash), the sending and receiving wallet addresses or accounts, and any fee you paid and which coin you paid it in.
If you need help tracking your cryptocurrency transactions, crypto tax software like CoinLedger can help. The platform is designed to make it easier than ever for you to generate a complete crypto tax report, no matter how many wallets and exchanges you’re using!
Is moving crypto taxable in other countries?
Most countries take a similar stance to the US when it comes to taxing wallet-to-wallet transfers. Transferring crypto between wallets you own is not considered taxable in the UK, Canada, or Australia, though in Australia, a network fee paid in crypto is itself a capital gains tax event.
How does CoinLedger deal with wallet-to-wallet transfers?
CoinLedger supports hundreds of cryptocurrency platforms, including exchanges like Coinbase and wallets like MetaMask.
If you’ve connected all the platforms you’re using, CoinLedger will automatically track all of your wallet-to-wallet transfers, including information like cost basis! If CoinLedger can’t match a transfer automatically, it flags the transfer on the Potential Bridges, Trades and Transfers tab so you can confirm it. If you dispose of your cryptocurrency in the future, the platform will calculate your gain/loss and the associated tax liability.
Why am I missing transactions on my tax return after a wallet-to-wallet transfer?
If you’ve transferred your cryptocurrency between wallets, you may get a ‘missing cost basis’ error while using crypto tax software.
Typically, this error occurs if you haven’t uploaded transactions from all of your wallets and exchanges — including those you didn’t use in the past calendar year.
Remember, your crypto tax software will need your original cost basis for all of your cryptocurrency to accurately calculate gains and losses.
To make sure your crypto tax software has all the relevant information, you’ll need to connect all of your wallets and exchanges and upload transactions from prior years. In addition, you should make sure that all wallet-to-wallet transfers have been labeled accurately within your software.
How CoinLedger can help
Looking to file your crypto taxes? Try CoinLedger, the platform that makes crypto tax reporting stress-free.
CoinLedger serves more than 700,000 crypto investors across the globe. With integrations with hundreds of exchanges and blockchains, you can generate a comprehensive tax report in just minutes!
Frequently asked questions
- Do crypto wallets report to the IRS?


- Is sending crypto to another wallet taxable?
- Is sending Bitcoin to someone else taxable?
- Is it better to keep your crypto in a wallet or an exchange?
- How much crypto can you send without paying taxes?
- Can the IRS see transfers between my wallets?
- How much crypto can I withdraw without paying taxes?


How we reviewed this article
All CoinLedger articles go through a rigorous review process before publication. Learn more about the CoinLedger Editorial Process.
CoinLedger has strict sourcing guidelines for our content. Our content is based on direct interviews with tax experts, guidance from tax agencies, and articles from reputable news outlets.
- Crypto assets (2023) https://viewpoint.pwc.com/dt/us/en/pwc/accounting_guides/crypto-assets-guide/assets/pwccryptoassetsguide0223.pdf
- Frequently Asked Questions on Virtual Currency Transactions (2023) https://www.irs.gov/individuals/international-taxpayers/frequently-asked-questions-on-virtual-currency-transactions
- Frequently asked questions on digital asset transactions (2025) https://www.irs.gov/individuals/international-taxpayers/frequently-asked-questions-on-digital-asset-transactions
- Instructions for Form 1099-DA (2026) https://www.irs.gov/instructions/i1099da
- Rev. Proc. 2024-28 (2024) https://www.irs.gov/pub/irs-drop/rp-24-28.pdf
- Notice 2026-20, Extension of Temporary Relief Under Section 1.1012-1(j)(3)(ii) (2026) https://www.irs.gov/pub/irs-drop/n-26-20.pdf
- Notice 2025-7 (2025) https://www.irs.gov/pub/irs-drop/n-25-07.pdf
- Rev. Proc. 2025-32 (2026 inflation adjustments) (2025) https://www.irs.gov/pub/irs-drop/rp-25-32.pdf
- Instructions for Form 709 (2025) https://www.irs.gov/instructions/i709
- 2025 Instructions for Form 1040 (2025) https://www.irs.gov/instructions/i1040gi
- Instructions for Form 8949 (2025) https://www.irs.gov/instructions/i8949
- Publication 529, Miscellaneous Deductions (2020) https://www.irs.gov/publications/p529
- Public Law 119-21 (One Big Beautiful Bill Act), sec. 70110 (2025) https://www.govinfo.gov/content/pkg/PLAW-119publ21/html/PLAW-119publ21.htm
- Public Law 119-5 (H.J. Res. 25) (2025) https://www.govinfo.gov/content/pkg/PLAW-119publ5/html/PLAW-119publ5.htm
- HMRC Cryptoassets Manual CRYPTO22100 (2025) https://www.gov.uk/hmrc-internal-manuals/cryptoassets-manual/crypto22100
- CRA: Reporting income from crypto-asset transactions (2025) https://www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/compliance/cryptocurrency-guide/income-crypto-transactions.html
- ATO: Crypto asset investments and tax (nd) https://www.ato.gov.au/other-languages/information-in-other-languages/investing/crypto-asset-investments-and-tax
- Frequently asked questions on gift taxes (2026) https://www.irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-gift-taxes
- What's new - Estate and gift tax (2026) https://www.irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax
- 26 CFR 1.1001-1 (Computation of gain or loss), para. (e) (nd) https://www.ecfr.gov/current/title-26/section-1.1001-1
- Digital assets (2026) https://www.irs.gov/filing/digital-assets
- H.R. 10357 (119th Congress), all actions (2026) https://www.congress.gov/bill/119th-congress/house-bill/10357/all-actions